By James Anderson September 24, 2026
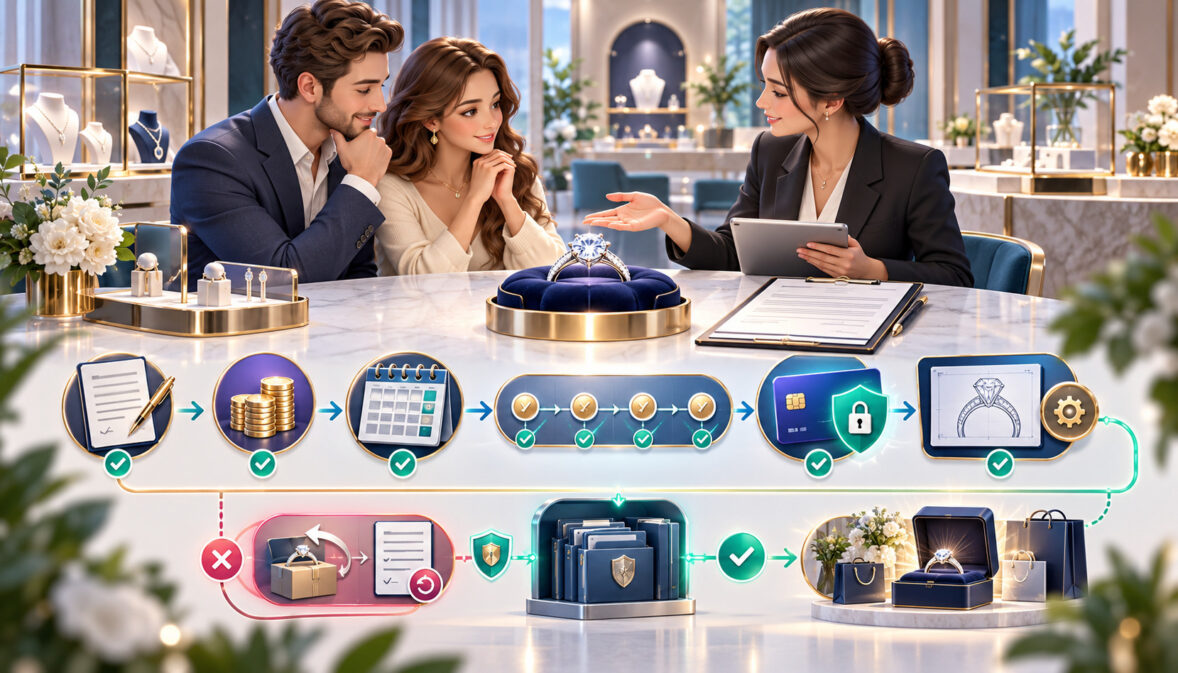
Jewelry store layaway rules are safest when the store keeps the merchandise until full payment, writes down payment dates and amounts, discloses cancellation and default consequences before taking money, follows applicable state refund law, and obtains express authorization for stored-card charges. Custom work does not automatically make every deposit legally non-refundable.
There is no single nationwide jewelry layaway contract that works identically in every state. The answer changes with the transaction structure, governing state law, whether the customer must continue paying, the degree of customization, the cancellation terms, and how future card payments are authorized.
Jewelry Store Layaway Rules: The Core Compliance Framework
Jewelry store layaway rules should begin with classification, not with a preprinted “non-refundable deposit” stamp.
Before taking the first payment, answer five questions:
- Is this actually layaway? Is the jewelry staying with the store until full payment?
- Which state’s law applies? Dedicated layaway statutes exist in some jurisdictions, while others rely more heavily on general consumer-protection, contract, refund-disclosure, and credit laws.
- What happens if the customer cancels?
- What happens after a missed payment or default?
- If a card will be charged later, what did the customer authorize?
The following is a best-practice framework plus a reminder to add any state-mandated terms. It is not a list of terms universally required in all 50 states.
| Issue | What the store should document |
| Merchandise | Exact item, SKU, stone, metal, size, engraving or custom specifications |
| Price | Total purchase price and applicable tax |
| Deposit | Initial payment |
| Installments | Amounts and due dates |
| Fees | Amount, purpose and trigger |
| Cancellation | Customer’s rights and consequences |
| Default | When default occurs and any applicable cure process |
| Refund | Original tender, cash, permitted store credit or lawful deduction |
| Delivery | When the customer receives the jewelry |
| Card-on-file | Customer authorization for later charges |
Keeping the merchandise until it is fully paid does not by itself answer every legal question, but it is a central feature of traditional layaway.
Layaway vs Financing vs BNPL
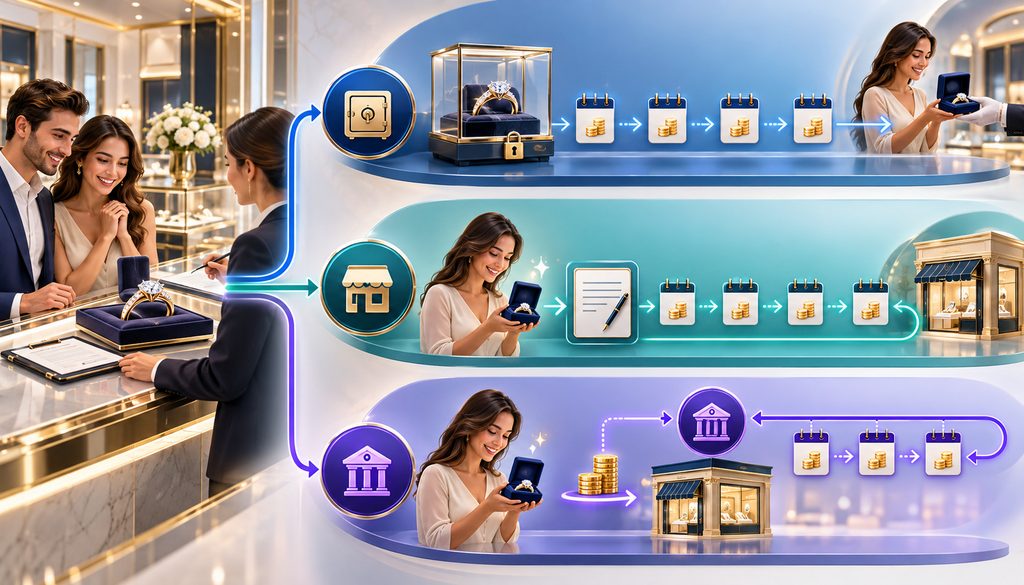
Traditional layaway usually differs from credit because the store retains the jewelry and the customer may be free to stop paying rather than becoming legally obligated for the remaining balance.
Under the CFPB’s Regulation Z definition of credit and Official Interpretations, traditional layaway is excluded from “credit” unless the consumer is contractually obligated to continue making payments.
The interpretation also explains that making prior payments non-refundable does not, by itself, turn the arrangement into credit; whether a continuing contractual obligation exists depends on applicable law.
| Feature | Traditional layaway | Store financing | Third-party BNPL |
| Jewelry received immediately? | Usually no | Often yes | Typically yes |
| Installments paid to | Jeweler | Jeweler/creditor | BNPL provider |
| Buyer obligated for remaining payments? | Generally not in classic layaway | Potentially yes | Depends on product |
| Credit law may apply? | Usually not under Reg Z if no continuing obligation | Potentially | Potentially; product-specific |
| Store keeps merchandise? | Yes until completed | Often no | Usually no |
| Missed payment | May end plan under disclosed/state rules | Debt/credit remedies may apply | Provider agreement governs |
BNPL should not be treated as simply “four-payment layaway.” Retailers considering multiple checkout choices should separately evaluate their jewelry financing options and payment methods, because possession timing, creditor identity, repayment obligations, and customer disclosures can differ substantially from traditional layaway.
Federal BNPL treatment has also changed. The CFPB’s 2024 interpretive rule concerning certain BNPL products was withdrawn on May 12, 2025, so merchants should not rely on descriptions of that rule as if it were current binding CFPB guidance in 2026.
If an installment payments jewelry store program gives the customer possession before full payment or makes the customer legally liable for the remaining balance, the program should be reviewed for applicable federal and state credit laws rather than assumed to be traditional layaway.
Is There an FTC Layaway Rule?
There is no comprehensive nationwide FTC layaway rule establishing identical refund, cancellation-fee and disclosure terms for every retailer.
Current FTC consumer guidance on layaway and pay-over-time plans tells buyers to examine payment terms, fees, missed-payment consequences, refund policies, and the written agreement, while also directing consumers to state authorities because applicable protections can differ by jurisdiction.
That guidance should not be mistaken for a federal statute granting every layaway customer the same refund right. Separately, Section 5 of the FTC Act prohibits unfair or deceptive acts or practices, so misleading statements about a store’s payment or cancellation terms can raise federal consumer-protection issues.
Layaway Agreement Disclosures Every Jewelry Store Should Address
The agreement should combine legally required disclosures in the applicable jurisdiction with operational details that reduce ambiguity.
A practical jewelry layaway agreement should address:
- Store legal/DBA name.
- Customer name and contact details.
- Agreement date.
- Detailed jewelry description.
- SKU, serial, style or model number.
- Metal, stone and custom specifications.
- Cash price.
- Sales-tax treatment.
- Initial deposit.
- Remaining balance.
- Number of installments.
- Each installment amount.
- Payment dates.
- Final-payment deadline.
- Layaway, service or setup fee.
- Late fee, only where lawful.
- Cancellation terms.
- Refund method.
- Any permitted cancellation deduction.
- Default definition.
- Any offered or legally required grace/cure period.
- Merchandise disposition after default.
- Custom-work commencement milestones.
- Card-on-file authorization.
- Customer and merchant acknowledgments.
Not every jurisdiction mandates all 25 items. For example, New York’s law specifies particular disclosures for covered layaway plans, while other states use materially different frameworks.
Layaway State Law Requirements: Why the Answer Changes by State
Layaway state law requirements range from detailed written-agreement and refund statutes to states where the retailer’s disclosed policy plays a much larger role.
The 50-state-and-D.C. review behind this article shows why a national jewelry chain should not simply copy one refund clause across every location.
| State/jurisdiction | Dedicated layaway rule? | Key requirement | Refund/cancellation theme | Primary source |
| New York | Yes | GBL §396-t covers purchases over $50 paid in four or more installments and requires specified written disclosures | Merchant’s refund policy and fees must be disclosed; statute does not create one blanket refund percentage | NY GBL §396-t |
| District of Columbia | Yes | Three or more agreed payments before delivery; extensive written disclosures | Full refund during first two weeks; later statutory cancellation deduction is capped | D.C. Code §28-3818 |
| Maryland | Yes | Written, signed layaway agreement; statutory disclosures and receipts | Seven-day penalty-free cancellation; detailed default rules; special orders treated differently | Md. Commercial Law §§14-1101–1107 |
| Ohio | Yes for covered transactions | Layaway above $500 requires a written contract with specified terms | Five-day written cancellation right plus statutory limits affecting later refunds/retention | Ohio Rev. Code §1317.22 |
| Wisconsin | No dedicated state layaway-policy statute identified by DATCP | Store establishes its policy | Written terms and records remain important; other contract/consumer laws may still apply | Wisconsin DATCP |
Several jurisdictions are therefore more prescriptive than those relying mainly on general law, but calling one state the universally “strictest” would oversimplify different statutory models.
New York is particularly useful for jewelry stores. Section 396-t requires covered plans to disclose the merchandise, total cost, layaway charges, duration, payment schedule and missed-payment consequences, refund policy, and when merchandise is isolated from inventory or ordered. An undisclosed layaway charge cannot simply be imposed later.
D.C. illustrates a different model. Its statute provides a two-week cancellation window with a full refund; after that period, a seller may retain no more than the lesser of 8% of the purchase price or $16. It also contains specific late-payment notice and fee provisions. Those figures are D.C.-specific, not suggested national fee percentages.
How Layaway Refund Rules Usually Break Down
Refund treatment must distinguish customer cancellation, customer default and merchant cancellation.
Depending on the jurisdiction and agreement, the result may be a full refund, a refund less a specifically permitted charge, or another treatment authorized by law. Some jurisdictions also regulate whether service charges, cancellation fees or store credits can be used.
A merchant that cannot supply the promised merchandise may face different obligations from a buyer who voluntarily cancels. Likewise, a missed installment is not necessarily immediate default: Maryland, for example, statutorily defines default after 15 days have elapsed from a missed scheduled payment.
Service Fees, Cancellation Fees and “Restocking” Fees
These labels should describe what actually happened.
A layaway service fee compensates for administering the plan. A cancellation fee addresses cancellation where state law and the agreement permit it. A custom design fee can relate to design services already performed, while nonreturnable material cost relates to actual materials committed to the project.
Calling every retained amount a “restocking fee” makes little sense when no finished item was ever returned to stock. Use accurate descriptions, disclose charges before payment, and confirm that state law permits the charge rather than adopting an arbitrary percentage.
Custom Jewelry Deposit Refund Policy
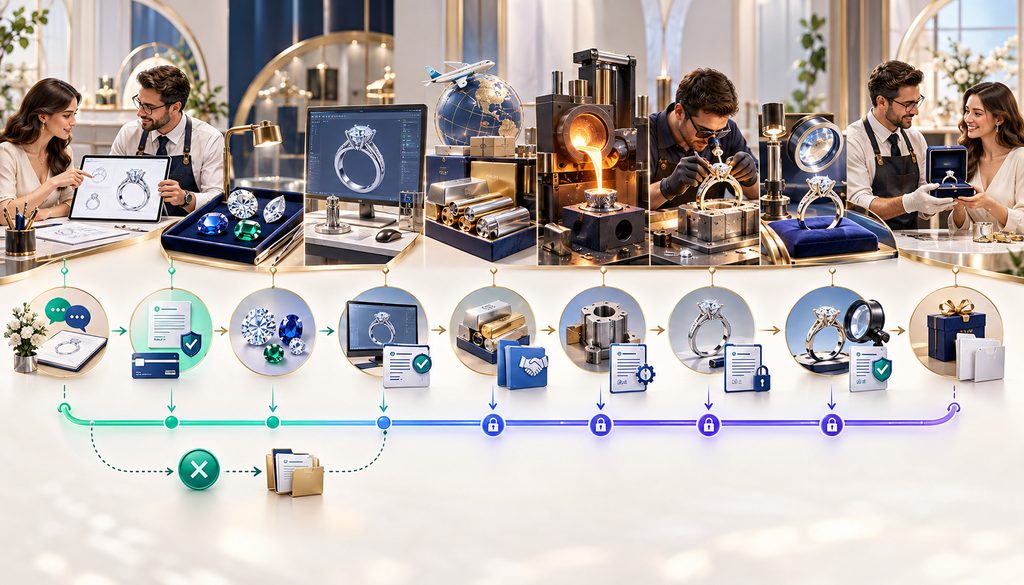
A custom-order deposit is not automatically non-refundable merely because the receipt uses the words “custom order.”
A defensible custom jewelry deposit refund policy depends on the governing law, what the customer agreed to, what work has occurred, materials already committed, resale potential and whether a stated damages provision is enforceable.
| Type | Resale potential | Work committed | Refund-policy consideration |
| Ordinary inventory | High | Little | Closest to conventional layaway |
| Special-order stock item | Moderate/high | Supplier order | Document supplier commitments |
| Resized inventory | Reduced | Alteration labor | Identify work actually performed |
| Engraved item | Low | Irreversible alteration | Obtain approval before engraving |
| Semi-custom ring | Variable | Design/material changes | Define milestones |
| Fully bespoke jewelry | Often low | Design, sourcing, fabrication | Tie payment treatment to documented stages |
When Can a Custom Jewelry Deposit Be Non-Refundable?
The merchant’s position may become stronger as genuine, disclosed commitments become irreversible—for example, individually sourced nonreturnable materials, approved CAD/design work, engraving, casting, fabrication, or an alteration that materially reduces resale potential.
None of those facts automatically overrides state law.
A better agreement defines what portion becomes earned at particular stages, which actual material commitments may be retained, what happens before production starts, and what happens after irreversible work begins.
The Uniform Commercial Code reinforces the need for precision. New York’s enacted UCC §2-201 contains a specially manufactured goods exception that can make an otherwise insufficiently documented contract enforceable when specified conditions are met.
But that provision concerns the statute of frauds; it does not say that every custom jewelry deposit is automatically forfeited.
New York UCC §2-718 separately addresses liquidated damages and deposits: an unreasonably large liquidated-damages amount is void as a penalty, and buyer restitution may be available subject to the seller’s lawful offsets and remedies. Other states’ enacted UCC provisions and case law must be checked separately.
Maryland provides another useful illustration. Its statute specifically defines certain special-order goods and directs sellers to applicable law and UCC remedies when a buyer defaults on a special-order transaction rather than declaring every special-order payment automatically forfeited.
What Happens When a Customer Stops Paying Mid-Plan?
A missed payment should trigger the process written into the agreement and required by state law—not an improvised forfeiture.
Treat these events separately:
- Missed installment: record the delinquency.
- Late but curable payment: observe any contractual or statutory cure period.
- Customer cancellation: apply the governing cancellation/refund terms.
- Store-declared default: declare it only when the agreement and law permit.
- Expired layaway: follow the disclosed expiration procedure.
- Merchant cannot supply: apply the rules governing seller cancellation or nonperformance.
The agreement should state how notice is sent, when merchandise returns to inventory, and what happens to money already paid. Do not assume that forfeiting every prior payment is enforceable.
Installment Payments at a Jewelry Store
For installment payments, jewelry store operators generally have three practical choices: customers manually initiate every payment, the store sends payment links, or the customer authorizes scheduled card-on-file charges.
Because these plans often involve expensive merchandise, the workflow should also fit the store’s high-value jewelry transaction processing controls, including authorization records, receipts, settlement tracking, and dispute documentation.
Manual payments provide the clearest customer initiation but create more follow-up. Payment links preserve customer control while reducing phone handling. Automatic stored-card installments are convenient, but they create card-network obligations that cannot be treated as an internal bookkeeping setting.
Card-on-File and Stored-Credential Compliance
NETWORK REQUIREMENT: card-network stored-credential rules are separate from state layaway law.
Under the current Visa stored-credential requirements, a merchant must obtain the cardholder’s express informed consent before storing credentials for future use and must properly identify subsequent stored-credential transactions.
For installment arrangements, the authorization and payment terms should be documented before later merchant-initiated charges begin.
The agreement includes transaction information such as the goods or services, total purchase price and cancellation/refund terms, plus stored-credential terms such as how charges are determined, timing or frequency, use of the credential and how changes will be communicated.
Visa also requires merchants to retain the agreement information for the agreement’s duration and use the appropriate stored-credential transaction indicators.
Mastercard similarly treats credential-on-file use as something the cardholder expressly authorizes. Its June 9, 2026 Transaction Processing Rules separately identify installment transactions, subscriptions, standing orders and unscheduled credential-on-file transactions.
Installment Is Not the Same as Recurring
A finite jewelry payment schedule should not casually be coded as a subscription.
Visa defines an Installment Transaction as a series of transactions for a single purchase or debt over a fixed period. Mastercard’s C104/M104 installment categories likewise cover a single purchase with a known amount, set frequency and specified duration, while Mastercard describes recurring payments as ongoing arrangements without a specified end date.
The merchant should therefore confirm with its gateway and acquirer that the proper cardholder-initiated, installment, recurring, unscheduled credential-on-file and merchant-initiated indicators are being transmitted.
Failed Card Payment Workflow
If an authorized scheduled charge declines:
- Record the decline.
- Do not repeatedly “hammer” the card.
- Follow the network/acquirer’s current resubmission rules.
- Notify the customer through the agreed channel.
- Allow any required or contractual cure period.
- Collect updated credentials through a secure payment system.
- Document schedule changes or new authorization.
- Apply the layaway default policy only when legally permitted.
Visa currently requires written notice after a declined merchant-initiated stored-credential transaction and at least seven calendar days for the cardholder to pay by other means. Mastercard retry treatment depends on the issuer’s response and Merchant Advice Code, so a jeweler should not invent a universal retry count.
Keep Card Data Out of Layaway Paperwork
BEST PRACTICE: use a processor or gateway’s tokenized card-on-file function instead of writing complete card numbers on layaway forms, spreadsheets or emails.
PCI DSS is a payment-industry security standard, not a federal layaway statute. One especially clear requirement is that CVV/CVC security codes must never be stored after authorization, even in encrypted form.
Recordkeeping, Refunds and Payment Disputes
Good documentation reduces factual disputes but does not guarantee a legal or chargeback win.
Keep the agreement, jewelry specifications, CAD/design approvals, stone and material selections, card authorization, receipts, transaction IDs, schedule, customer communications, changes, cancellation request, missed-payment notices, supplier commitments, alteration or engraving approval, refund records and delivery/pickup acknowledgment together.
These records can matter in consumer complaints, processor reviews, card disputes, attorney-general inquiries, and contract litigation.
For card disputes specifically, a documented jewelry chargeback management process helps the team organize authorization, refund-policy, custom-work, communication, and delivery evidence without confusing card-network procedures with the underlying contract dispute.
A signed “non-refundable” clause does not guarantee that a jeweler will defeat a chargeback. Card-network dispute procedures and the underlying legal question of whether money may be retained are related but distinct. Useful evidence includes the agreement, disclosed refund terms, customer approvals, custom-work records, payment history and delivery evidence.
Hypothetical Payment Schedules
Custom-ring example — illustrative only: A $6,000 bespoke ring might use $1,500 at order, $1,500 after written/CAD approval, $1,500 at a documented production milestone and $1,500 before pickup. These amounts are neither legally required nor presented as an ideal percentage; the point is to connect payments to real work and commitments.
Inventory-layaway example — illustrative only: A $2,000 stocked ring could use $500 at enrollment followed by three scheduled $500 payments, with possession remaining with the store until the agreed price is fully paid.
Illustrative disclosure only — adapt to governing law:
“Your payment schedule, cancellation rights, refund eligibility, custom-work milestones and any permitted fees are stated here before your first payment. Scheduled card charges will be made only under the stored-payment authorization described in this agreement.”
Common Layaway Misconceptions
| Myth | Reality |
| Federal law gives every customer the same layaway rights. | State law varies. |
| There is one FTC layaway rule for all stores. | FTC guidance is not a universal federal refund code. |
| “Non-refundable” means the store can always keep the money. | Enforceability depends on governing law and facts. |
| Custom jewelry deposits are automatically non-refundable. | Customization alone does not decide the issue. |
| Four payments automatically make layaway BNPL. | Transaction structure matters, not a slogan or payment count alone. |
| A saved card can be charged whenever payment is due without consent. | Stored-credential use requires authorization and proper network treatment. |
| One declined installment means every prior payment can be kept. | Default and refund rules must be checked. |
| A signed contract overrides consumer-protection law. | Statutory protections can limit contract terms. |
| Successful card authorization proves the refund policy is enforceable. | Authorization confirms payment approval, not legal enforceability. |
Common Jewelry-Store Layaway Mistakes
| Mistake | Why it creates risk | Better control |
| Oral terms | Hard to prove | Written agreement |
| “All deposits non-refundable” stamp | Overbroad | Stage-specific policy |
| No custom milestone | Unclear earned costs | Document design/production stages |
| Employee promises vary | Inconsistent expectations | Standard staff process |
| Handwritten card numbers | Security exposure | Tokenized vault |
| Automatic charges without consent | Network/dispute risk | Recorded authorization |
| Verbal date changes | Weak audit trail | Written confirmation |
| No supplier records | Custom losses hard to substantiate | Save POs/invoices |
| Calling everything “restocking” | Misdescribes charge | Accurate fee description |
| Keep all payments and immediately restock | Potential refund/damages issue | Apply governing law |
| Same policy in every state | Ignores local requirements | State-law matrix |
A Practical Setup Workflow for Jewelers
- Decide which products qualify for layaway.
- Separate inventory layaway from custom orders.
- Identify every state where the program is offered.
- Research each state’s current rules.
- Set payment amounts and dates.
- Define cancellation and default stages.
- Approve fees only after legal review.
- Map custom-production milestones.
- Draft plain-language disclosures.
- Configure POS/customer-account fields.
- Enable tokenized stored credentials.
- Capture cardholder consent.
- Automate receipts and reminders.
- Build a declined-payment workflow.
- Create cancellation/refund reason codes.
- Train sales associates.
- Store the agreement and payment history together.
- Review complaints and disputes quarterly.
- Recheck state statutes and network rules periodically.
Keep Staff Explanations Consistent
Sales associates should not improvise refund promises at the counter.
Before accepting money, staff should point the customer to the total price, payment dates, cancellation terms, applicable custom-work milestone, refund treatment and any automatic-payment authorization. Material changes should be confirmed in writing rather than handled through an undocumented conversation.
FAQs
Are jewelry-store layaway deposits refundable?
Sometimes, but there is no single nationwide answer. State law and the written agreement matter. D.C., Maryland and Ohio, for example, have specific statutory cancellation/refund provisions for covered transactions, while Wisconsin’s consumer agency says the state has no law specifically regulating layaway policies. A retailer should identify the governing jurisdiction before deciding what may be retained.
Is there a federal FTC layaway rule?
There is no comprehensive FTC rule establishing one national set of layaway refund and cancellation terms. The FTC publishes consumer guidance about deposits, fees, refunds, missed payments and contracts, while Section 5 of the FTC Act prohibits unfair or deceptive practices. State statutes and consumer-protection rules remain central to layaway rights.
What should a jewelry layaway agreement include?
At minimum, identify the jewelry, total price, payments, dates, fees, cancellation and default treatment, refund policy and delivery conditions. Custom orders should also identify specifications and production milestones.
If a card is stored for later charges, document that authorization separately and ensure the gateway sends the appropriate network indicators. Applicable state law may prescribe additional disclosures.
Can a jeweler make a custom-order deposit non-refundable?
Possibly in some circumstances, but the words “non-refundable” do not settle the issue. Governing state law, disclosure, actual work performed, nonreturnable materials, resale potential and damages rules can all matter.
For custom jobs, the agreement is usually clearer when it ties retained amounts to documented design, materials and fabrication stages rather than declaring every dollar forfeited immediately.
What happens if I stop paying on a jewelry layaway plan?
The agreement and applicable state law determine the next step. A missed payment may lead to notice, a cure period, cancellation or default, followed by the refund or deduction permitted in that jurisdiction. It should not automatically be assumed that the store can keep every payment. Some states prescribe their own timing and remedies.
Is layaway the same as financing or BNPL?
No. Traditional layaway generally leaves the merchandise with the merchant until it is fully paid and, under Regulation Z’s current interpretation, is not “credit” unless the consumer is contractually obligated to continue paying. Financing and BNPL can involve different possession, repayment and legal structures.
Can a jewelry store automatically charge my card every month?
Only when the arrangement has been properly authorized and processed under applicable payment rules. Visa and Mastercard require consent for stored-credential use and distinguish different transaction types.
A finite installment arrangement should not simply be treated as an open-ended subscription. Customers should be told how much will be charged, or how it is calculated, and when appropriate charges occur.
Can a jeweler charge a cancellation or restocking fee?
Sometimes, but the answer is jurisdiction-specific. Certain statutes expressly regulate cancellation deductions or fees; other jurisdictions allow greater contractual flexibility subject to consumer-protection and contract law.
A merchant should disclose the fee before taking payment and use an accurate description—a cancellation charge is not automatically a “restocking fee.”
What records should a jewelry store keep for layaway payments?
Keep the signed or electronic agreement, payment authorization, item description, custom specifications, approvals, transaction receipts, installment history, customer communications, supplier or material commitments, alteration records, cancellation/default notices, refunds and pickup or delivery evidence. These records help reconstruct what happened if a consumer, issuer, processor or regulator later questions the transaction.
Clear Layaway Terms Protect Both the Jeweler and the Customer
Effective jewelry store layaway rules start by identifying the transaction before accepting money: true layaway, store financing, third-party credit or a custom-order arrangement can raise different legal issues.
Put the entire payment schedule and cancellation treatment in writing. Distinguish stocked merchandise from engraving, resizing, special ordering and genuine custom fabrication, and connect any retained custom-order amount to clearly disclosed, documented work or costs rather than a vague “non-refundable” stamp.
When installments use a stored card, obtain proper consent, use the processor’s correct stored-credential treatment and keep the payment record with the underlying agreement. The practical goal is simple: the customer should know what happens at every stage, and the store should be able to prove exactly what was agreed and performed.