By James Anderson September 23, 2026
A $12,000 card sale can cost several hundred dollars under flat-rate pricing. Interchange-plus exposes the underlying card/network cost plus processor markup. Qualifying commercial large-ticket programs can materially reduce interchange, but a $12,000 personal premium credit card does not automatically qualify simply because the engagement ring carries a five-figure price.
For jewelry large ticket credit card processing, the crucial distinction is between a large transaction and a transaction that qualifies for a network-defined large-ticket interchange program.
Visa and Mastercard publish separate consumer and commercial interchange structures, so the card product, processing environment, data, merchant setup, authorization, and qualification rules can matter as much as the dollar amount.
Jewelry Large Ticket Credit Card Processing: What a $12,000 Sale Can Cost
A jeweler’s processing expense normally contains several layers:
Total transaction processing cost = interchange + network/pass-through fees + processor markup + transaction fee + applicable ancillary costs
Interchange is the amount transferred between acquiring and issuing institutions under network rules. Visa specifically distinguishes interchange reimbursement fees from the merchant discount paid by the merchant to its financial institution.
Under interchange-plus, those components are generally more visible. Under flat-rate pricing, several underlying costs may instead be absorbed into one processor-set percentage.
Monthly gateway, statement, platform, PCI, or account fees should not arbitrarily be assigned to a single $12,000 transaction. If a CFO wants a fully loaded effective rate, allocate those costs consistently across the relevant period.
Worked Example: $12,000 Ring Under Flat-Rate Pricing
Assume an illustrative processor price of 2.9% + $0.30. This is a hypothetical example, not a universal market rate.
Transaction amount: $12,000
$12,000 × 2.9% = $348.00
$348.00 + $0.30 = $348.30
The processing charge is therefore $348.30, producing an effective transaction rate of 2.9025%.
$12,000 − $348.30 = $11,651.70
That is the simplified net settlement before refunds, holds, reserves, adjustments, or other separately billed charges.
Flat-rate pricing has one obvious advantage: the merchant can predict the fee without identifying the precise interchange category. But applying the same percentage to every dollar becomes financially significant on five-figure sales.
The Same Ring Under Interchange-Plus Pricing
Interchange-plus separates the network-defined interchange cost from the processor’s own markup:
Interchange + applicable network fees + disclosed processor markup
That means two customers can buy identical $12,000 rings and create different costs.
Using Visa’s U.S. interchange schedule effective April 18, 2026, a qualifying card-present Product 2 transaction is listed at 1.65% + $0.10 for Visa Signature but 2.30% + $0.10 for spend-qualified Visa Infinite. These are consumer interchange categories, not large-ticket commercial rates.
For the spend-qualified Visa Infinite example:
$12,000 × 2.30% = $276.00
$276.00 + $0.10 = $276.10 interchange
That $276.10 is not the merchant’s finished processing bill. Network/pass-through charges and the processor’s contracted markup still have to be added.
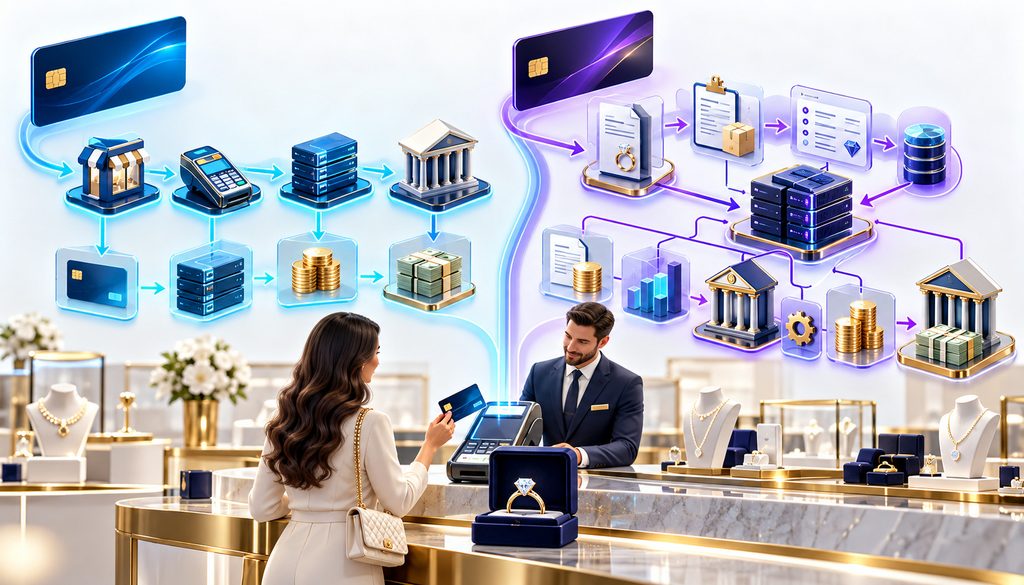
A qualifying commercial transaction could follow a completely different path and, as the examples below show, potentially produce substantially lower interchange.
Does a $12,000 Engagement Ring Qualify for Large-Ticket Interchange?
Not simply because the transaction is $12,000.
“Large ticket” is a particular interchange classification. An ordinary consumer buying an engagement ring on a personal Visa Infinite, Visa Signature, Mastercard World Elite, or another rewards product remains a consumer-card transaction unless the applicable network rules say otherwise.
A business purchase can be different. A corporate buyer purchasing awards, gifts, inventory, watches, jewelry components, or other legitimate business goods on an eligible purchasing or commercial account may potentially meet a commercial-card program’s requirements.
| Characteristic | Premium consumer card | Commercial/purchasing card |
| Cardholder/use | Individual consumer | Business or organization |
| Typical purpose | Personal spending | Business procurement/payables |
| Enhanced Level II/III data | Usually irrelevant to consumer interchange | May matter to qualifying programs |
| Large-ticket eligibility | Not created by transaction size | Possible under specific programs |
| Interchange family | Consumer | Commercial |
| Rewards | May carry premium rewards/benefits | May offer corporate controls/rewards |
| Processor requirements | Normal consumer qualification rules | May require enhanced data/program support |
Visa’s current schedule explicitly places Commercial Product Large Ticket and Straight Through Processing inside its Corporate and Purchasing Interchange Fees, while Mastercard publishes World Elite in its consumer table separately from Large Market Credit and Commercial Payments Account programs.
[Expert Quote Placeholder]
Editorial direction: Insert a verified quote from a payments/acquiring professional explaining why jewelers should distinguish card-product qualification from transaction amount.
Large Ticket Program Jewelry Store: Visa
The current Visa U.S. Interchange Reimbursement Fees schedule is effective April 18, 2026.
| Visa program | Eligible card/product | Transaction range | Published interchange | Key qualification |
| Commercial Product Large Ticket | Purchasing/Corporate T&E | Range not stated in that table | 1.30% + $35 | Commercial-product qualification |
| STP Tier 2 | STP commercial transaction | $7,000–$14,999.99 | 1.30% + $35 | STP participation and qualification |
| STP Tier 3 | STP commercial transaction | $15,000–$49,999.99 | 1.10% + $35 | STP qualification |
| Large Purchase Advantage | Visa LPA purchasing virtual account, CNP | $10,000.01–$25,000 | 0.70% + $49.50 | Specialized card-absent commercial-payables product |
Visa lists STP Tier 2 at 1.30% + $35. An eligible $12,000 transaction would therefore produce:
$12,000 × 1.30% = $156
$156 + $35 = $191 interchange
This calculation shows network interchange for a qualifying transaction, not the complete merchant statement cost.
STP is not simply a threshold discount. Visa’s current rules require an acquirer participating in Straight Through Processing to register with Visa and sign an STP Participation Agreement.
Visa Large Purchase Advantage is even more specialized. Visa requires the card to be a virtual credit account used in a Commercial Payables environment, and LPA transactions must be card-absent. A personal Visa Infinite card in a jewelry store therefore cannot be treated as an LPA transaction merely because the purchase exceeds $10,000.
Mastercard Large-Ticket Programs
The Mastercard 2026–2027 U.S. Region interchange bulletin is effective April 17, 2026.
For Large Market Credit, Mastercard currently publishes Data Rate I at 2.70% + $0.10, Data Rate II at 2.50% + $0.10, Data Rate III at 1.90% + $0.10, and Large Ticket at 1.45% + $35. Those entries are commercial rates; World Elite appears separately in Mastercard’s consumer-credit table.
The public bulletin does not state a transaction threshold beside that Large Market Credit Large Ticket row. A processor should therefore substantiate the applicable qualification criteria rather than asserting that every transaction above an arbitrary dollar figure receives 1.45% + $35.
Mastercard also publishes explicit tiers for its Commercial Payments Account:
- Less than $10,000: commercial rates apply.
- $10,000–$25,000: Large Ticket 1 at 1.20%.
- $25,000.01–$100,000: 1.00%.
- $100,000.01–$500,000: 0.90%.
For a genuinely qualifying $12,000 Commercial Payments Account transaction:
$12,000 × 1.20% = $144 interchange
No fixed-dollar component is shown for that published tier. Again, $144 is interchange—not total merchant cost.
Worked Comparison: One $12,000 Sale, Different Pricing Paths
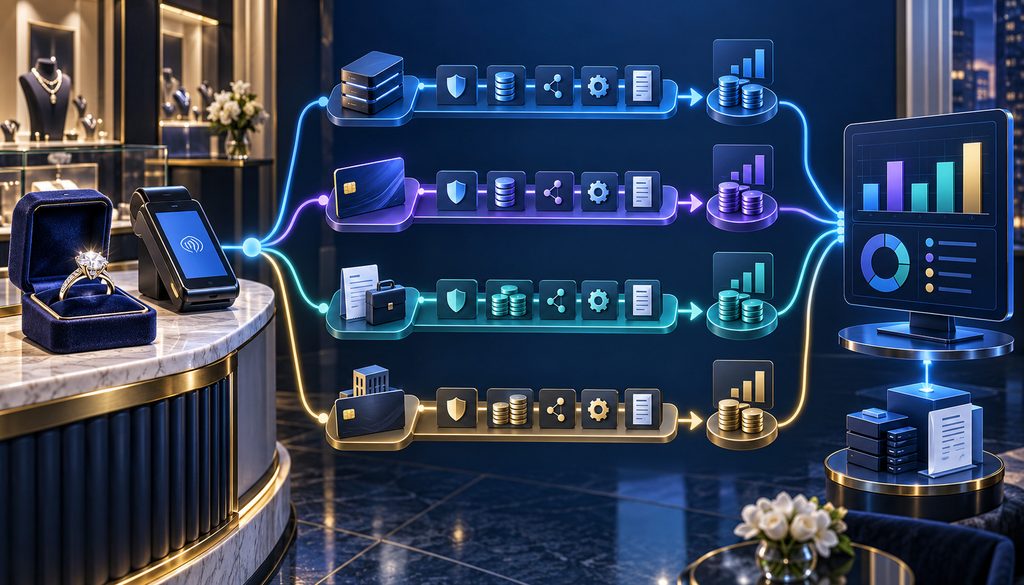
The table illustrates why “high value transaction fees jeweler” cannot be answered with one universal percentage.
| Scenario | Pricing basis | Assumption | Cost shown | Important caveat |
| Flat-rate plan | Hypothetical processor price | 2.9% + $0.30 | $348.30 total illustrative processor charge | Processor-specific |
| Visa premium consumer | Current Visa consumer interchange | Visa Infinite spend-qualified Product 2, 2.30% + $0.10 | $276.10 interchange | Markup/network fees excluded |
| Visa commercial STP | Current STP Tier 2 | 1.30% + $35 | $191 interchange | Must genuinely qualify |
| Mastercard Commercial Payments Account | Current Large Ticket 1 | 1.20% | $144 interchange | CPA product/program required |
These figures are deliberately not presented as like-for-like final merchant costs. The flat-rate example is a processor price, while the other three calculations show published interchange before additional applicable charges.
Why Premium Rewards Cards Can Make Jewelry Sales Expensive
Jewelers can encounter a meaningful mix of premium consumer and commercial cards on high-value sales, but there is no need to invent a jewelry-specific card-mix percentage.
The relevant point is that product classification matters. Mastercard’s April 2026 schedule, for example, lists World Elite Merit III Base consumer credit at 2.30% + $0.10, while its commercial programs use entirely different tables.
Card-present versus card-not-present qualification, authorization, merchant category, transaction data, and downgrades can further change the result.
What Level II and Level III Data Actually Changes
Enhanced data is primarily a commercial-payment concept, not a trick for turning a consumer engagement-ring purchase into cheap interchange.
Visa defines U.S. Level II enhanced data for commercial transactions as including fields such as sales-tax amount and customer code. Its enhanced transaction-level data can also include item descriptions, unit costs and quantities.
Level III commonly extends into invoice/order and line-item information. The POS or gateway must capture the data, the processor/acquirer must transmit it correctly, and the underlying card and interchange program must be eligible.
A terminal advertising “Level III capability” does not guarantee Level III pricing on every transaction.
Why a Processor Can Flag a $12,000 Sale Even When the Card Approves
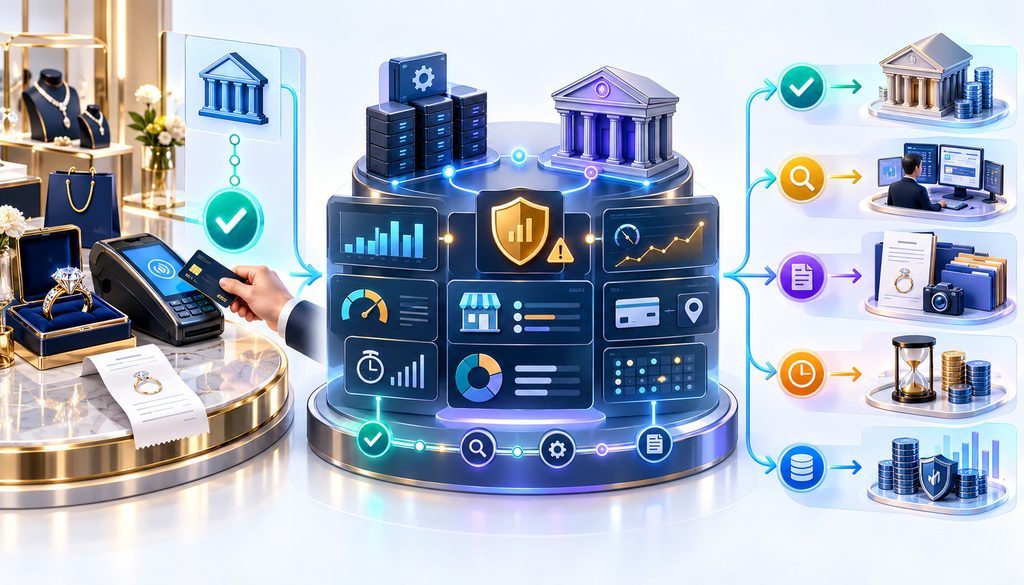
Issuer authorization answers whether the issuer approves a transaction against the card account under its rules. It does not obligate an acquiring processor to ignore the merchant’s underwriting profile.
A jewelry merchant account may have expected average-ticket, maximum-ticket or monthly-volume parameters. An unusual sale may therefore prompt additional fraud review, invoice requests, delivery verification, delayed settlement, a funding hold, or reserve analysis even after an authorization code is returned.
Because unusually large sales can fall outside a merchant account’s normal ticket and volume profile, jewelers should make sure their procedures for handling high-value jewelry transactions securely account for authorization, processor review, settlement timing, transaction limits, and supporting documentation.
Velocity Limits on Large Jewelry Sales
Velocity limits large jewelry sales when processor or acquirer risk controls see activity materially different from the merchant’s approved profile.
Possible triggers include several unusually large sales in a short window, a sharp increase in average ticket, monthly volume exceeding underwriting projections, heavy card-not-present volume, a new processing history, or unusual refund behavior.
These are not universal Visa or Mastercard interchange limits. They may be processor-, acquirer-, underwriting-, or merchant-agreement-specific controls.
Floor Limits Are Not the Same as Merchant Account Limits
A network floor limit is not a processor’s approved maximum ticket.
Visa currently defines a floor limit as a currency amount established for a transaction above which online authorization is required.
Keep these concepts separate:
- Floor limit: network authorization concept.
- Authorization: issuer’s approval decision.
- Available credit: cardholder-account constraint.
- Maximum-ticket profile: merchant underwriting parameter.
- Velocity rule: processor/acquirer risk control.
A processor saying a merchant is approved for a $10,000 maximum ticket is therefore describing something different from a network floor limit.
What Happens on a $50,000 or $100,000 Jewelry Sale?
Percentage-based pricing becomes particularly visible as transaction values rise.
At a hypothetical 3% effective processing cost:
$50,000 × 3% = $1,500
$100,000 × 3% = $3,000
That does not mean a jeweler should automatically steer every large customer away from cards. It means alternative-payment economics deserve a transaction-specific comparison.
| Payment route | Merchant-cost structure | Customer convenience | Settlement/reversal considerations | Operational friction |
| Credit card | Often percentage-driven plus fees | High | Authorization, disputes and processor funding rules apply | Low |
| ACH | Provider-specific | Moderate | Returns/fraud rules depend on transaction type | Moderate |
| Wire | Bank/provider-specific | Moderate | Verification and fraud controls still matter | Higher |
| Check | Banking/operational cost varies | Lower | Counterfeit, return and clearance risk | Higher |
Should a Jeweler Offer a Wire or Check Incentive?
An incentive can make economic sense when the retained card-processing savings exceed the cost and risk of the alternative payment.
A useful framework is:
Maximum rational incentive = avoidable card-processing cost − alternative-payment cost/risk − desired retained savings
If a six-figure card transaction would create an estimated $2,500 processing expense while an authenticated wire costs the merchant materially less, an incentive below the avoidable card cost could potentially benefit both sides.
Before establishing a policy, verify the merchant agreement, network requirements, state law, advertised-price rules, debit treatment, and any surcharge or discount disclosure requirements.
Cash Discount vs Credit-Card Surcharge
A cash or qualifying alternative-payment discount reduces a bona fide regular price. A surcharge adds a fee associated with using a credit card.
Visa’s current U.S. guidance expressly distinguishes the two, and Mastercard maintains separate surcharge requirements. They should not be relabeled to make one appear to be the other.
Because network rules and state requirements can change, a jeweler should validate the current rules before publishing prices or launching an incentive program.
Reduce Processing Cost on a Five-Figure Sale
To reduce processing cost five figure sale decisions should start with actual statement data, not a salesperson’s advertised “large-ticket rate.”
- Pull three months of merchant statements.
- Identify actual card-brand and product mix.
- Separate consumer, debit and commercial activity.
- Calculate the true effective processing rate.
- Separate processor markup from interchange where possible.
- Identify downgrades.
- Verify the merchant category code.
- Confirm EMV/card-present qualification.
- Confirm whether Level II/III data is supported.
- Identify genuine commercial large-ticket transactions.
- Review maximum-ticket and monthly-volume underwriting.
- Compare alternative-payment economics.
- Negotiate processor markup using actual volume.
- Recalculate expected savings using the real card mix.
Visa’s April 2026 Merchant Data Standards Manual identifies MCC 5944 as “Jewelry Stores, Watches, Clocks, and Silverware Stores.” A retailer should still verify the MCC actually assigned to its merchant account rather than assuming it from the business name.
Questions to Ask Before Moving High-Ticket Volume to Any Program
Ask the processor to answer these questions in writing:
- Which Visa and Mastercard categories are you calling “large ticket”?
- Are they consumer or commercial programs?
- Is my jewelry MCC eligible?
- Which exact card products qualify?
- What ticket threshold applies?
- Is Level II or Level III data required?
- Can my POS and gateway transmit every required field?
- What processor markup is added?
- Which network/pass-through fees remain?
- Is there a fixed-dollar interchange component?
- What happens when qualification fails?
- What interchange applies after a downgrade?
- What is my approved maximum ticket?
- What monthly volume was underwritten?
- Are there processor/acquirer velocity controls?
- Can a large transaction trigger manual funding review?
- Can reserves apply under my agreement?
- What is the normal funding treatment for large transactions?
- Are there early-termination or minimum charges?
- Can you show the qualifying category on my actual merchant statement?
Red Flags in a “Large-Ticket” Processing Proposal
Be cautious when a proposal quotes one unusually low percentage without identifying the card product, calls every transaction above $10,000 “large ticket,” or compares its interchange rate against another processor’s fully loaded rate.
Other warning signs include promises that Level III lowers every consumer-card sale, hidden processor markup, omitted fixed components, unspecified downgrade pricing, “unlimited” ticket sizes without underwriting review, and U.S. proposals supported with Canadian or European interchange charts.
Interchange on an Engagement Ring Sale: Three Mistakes Jewelers Make
The first interchange on engagement ring sale mistake is assuming the receipt amount determines interchange. Product and qualification rules matter.
The second is comparing a flat-rate processor’s total transaction charge against interchange alone. That omits processor markup and applicable network fees from the interchange-plus side.
The third is assuming an affluent customer carrying a premium card is using a commercial card. Visa Infinite and Mastercard World Elite consumer products are not automatically corporate or purchasing cards.
A fourth common mistake is changing processors based on a theoretical large-ticket category that represents only a tiny fraction of the store’s actual transactions.
Common Myths About Jewelry Large-Ticket Processing
| Myth | Reality |
| “My $12,000 ring automatically gets a large-ticket rate.” | Amount alone does not establish qualification. |
| “Level III lowers every expensive card transaction.” | Enhanced data principally matters to eligible commercial programs. |
| “A premium rewards card is the same as a commercial card.” | Consumer and commercial products have separate interchange structures. |
| “The processor’s 2.9% is all interchange.” | Flat-rate pricing is processor pricing, not an interchange rate. |
| “If the issuer approves $50,000, my processor must fund it.” | Acquirer funding review can still apply. |
| “A floor limit is my processor’s maximum ticket.” | A floor limit is an authorization concept. |
| “Splitting a transaction always reduces interchange.” | It can increase fees or create authorization/risk issues; do not split to evade controls. |
| “Wire is always better than card.” | Cost, fraud, convenience and settlement needs differ by transaction. |
Real-World Example: Independent Jeweler Reviews Five-Figure Sales
Consider a hypothetical independent jeweler processing $150,000 in card volume each month. Its normal ticket is $1,500, but it processes several $10,000–$25,000 purchases and occasionally serves a commercial buyer.
The owner first discovers that most five-figure sales are still premium consumer cards. Those sales cannot simply be moved into a commercial large-ticket category.
A smaller subset uses eligible commercial payment products. The jeweler then asks its processor which transactions can qualify for the current Visa or Mastercard commercial programs, whether the gateway transmits the necessary data, and what happens on failed qualification.
The CFO separately negotiates processor markup, updates the acquiring bank on the genuine high-ticket profile, and reviews alternative-payment economics for extraordinary six-figure purchases.
That produces a much more credible savings model than applying one advertised “large-ticket” percentage to $150,000 of monthly volume.
FAQs
How much does it cost to process a $12,000 credit-card sale?
It depends on the processor’s pricing model and the card that qualifies. Under a hypothetical 2.9% + $0.30 flat rate, a $12,000 transaction costs $348.30.
Under interchange-plus, the underlying interchange could be materially different depending on whether the card is consumer, premium consumer, commercial, debit, card-present or card-not-present. Network fees and processor markup must also be included before calling an interchange-plus number the final cost.
What is a large-ticket interchange program?
A large-ticket program is a specific network interchange classification designed for qualifying transactions and card products. It is not simply a generic discount for an expensive receipt.
Visa’s current schedule contains commercial large-ticket, STP and specialized Large Purchase Advantage pricing, while Mastercard publishes commercial Large Market Credit and Commercial Payments Account programs. Each has its own product and processing requirements.
Does a $12,000 engagement ring automatically qualify for large-ticket interchange?
No. A consumer who buys a $12,000 engagement ring on a personal premium rewards card normally remains within the applicable consumer interchange framework. The transaction amount does not transform the card into a commercial product.
Qualification for commercial large-ticket programs depends on the network program, card type, merchant and processing setup, transaction criteria and required data.
Can Level III data lower jewelry processing fees?
Potentially, but primarily when an eligible commercial transaction and interchange program rewards the transmission of enhanced data. Level III information can include detailed invoice and line-item information.
A consumer credit card does not become commercial merely because the POS sends extra fields. The gateway, processor and acquirer must also transmit the data correctly.
Why do premium rewards cards cost jewelers more?
Some premium consumer products carry higher published interchange than other consumer categories. For example, Visa’s April 2026 Product 2 table lists different rates for spend-qualified Visa Infinite, Visa Signature and other product categories. The actual cost still depends on qualification, processing environment and processor pricing.
What is the difference between a floor limit and a transaction limit?
A network floor limit determines when online authorization is required under applicable network rules. A merchant-account transaction limit or maximum-ticket expectation is an underwriting or processor/acquirer parameter. They are different controls. A cardholder’s available credit and the issuer’s fraud decision are separate again.
Should a jeweler offer a discount for wire or check?
Possibly, when the avoidable card-processing expense substantially exceeds the economic cost and operational risk of the alternative. There is no universally correct discount percentage. Model the actual avoided cost first, then verify card-network rules, the merchant agreement, applicable law and advertised-price requirements before implementing the program.
How can a jeweler lower processing costs on five-figure sales?
Start with actual statements. Determine which five-figure transactions are consumer, debit and commercial; identify interchange and processor markup; check downgrades; verify MCC and EMV qualification; determine whether eligible commercial transactions can transmit enhanced data; and confirm high-ticket underwriting. Only then compare processors or commercial large-ticket programs.
The Cheapest $12,000 Transaction Is the One You Actually Qualify For
Flat-rate pricing makes a $12,000 jewelry transaction easy to calculate, but the percentage applies to the entire ticket. Interchange-plus makes the economics more visible because the underlying card-product cost and processor markup can be examined separately.
Genuine commercial large-ticket programs can materially lower interchange on eligible payments. Visa’s STP Tier 2 and Mastercard’s Commercial Payments Account Large Ticket 1 illustrate that potential—but neither makes an ordinary $12,000 consumer engagement-ring transaction a commercial payment.
For jewelry large ticket credit card processing, the practical takeaway is to analyze the cards customers actually use, the categories that actually appear on merchant statements, and the programs the merchant can actually qualify for. A defensible cost model based on real transaction mix is more valuable than the lowest rate printed on a processor proposal.